Nigeria's inflation rate soars to 28-year high


Nigerian President Bola Tinubu
Nigeria's inflation rate soared to more than 28-year high in May as higher food and transport prices continue to ravage the economy. This comes against the backdrop of the World Bank approving a $2.25 billion loan to support economic reforms in the country.
Data shows that consumer prices climbed to 33.95 per cent in May, compared with 33.7 per cent in April. Food inflation also rose to 40.66 per cent in May from 40.3 per cent in April. Depreciation of currency has also contributed to inflation. The local currency, the Naira, has dropped 70 per cent against the dollar since June last year.
This food crisis is largely driven by twomajor factors - partial removal of fuel subsidies and the floating of currency. This is also the worst economic crisis facing Nigeria in decades. The once-biggest African economy has now fallen to fourth place this year.
The bulk of the World Bank loan, $1.5 billion, is set to assist millions facing poverty; the rest will go to support tax reforms & safeguard oil revenues. Despite being a major oil producer, Nigeria has struggled with high imports, underinvestment, & mismanagement.
Bloomberg analysts are optimistic that some relief might be on the horizon. This is due to upcoming reforms around suspending import duties on certain essentials for six months and increasing minimum wages. Annual inflation is expected to gradually slow to around 32 per cent at year-end, while the rate-hike cycle is expected to end in July.
Nigerians are struck in the 'future land' while their present is clouded with unprecedented turmoil. The country is facing its worst cost-of-living crisis in years. However, Nigeria's president, Bola Tinubu,said his economic reforms will continue despite increasing hardships.
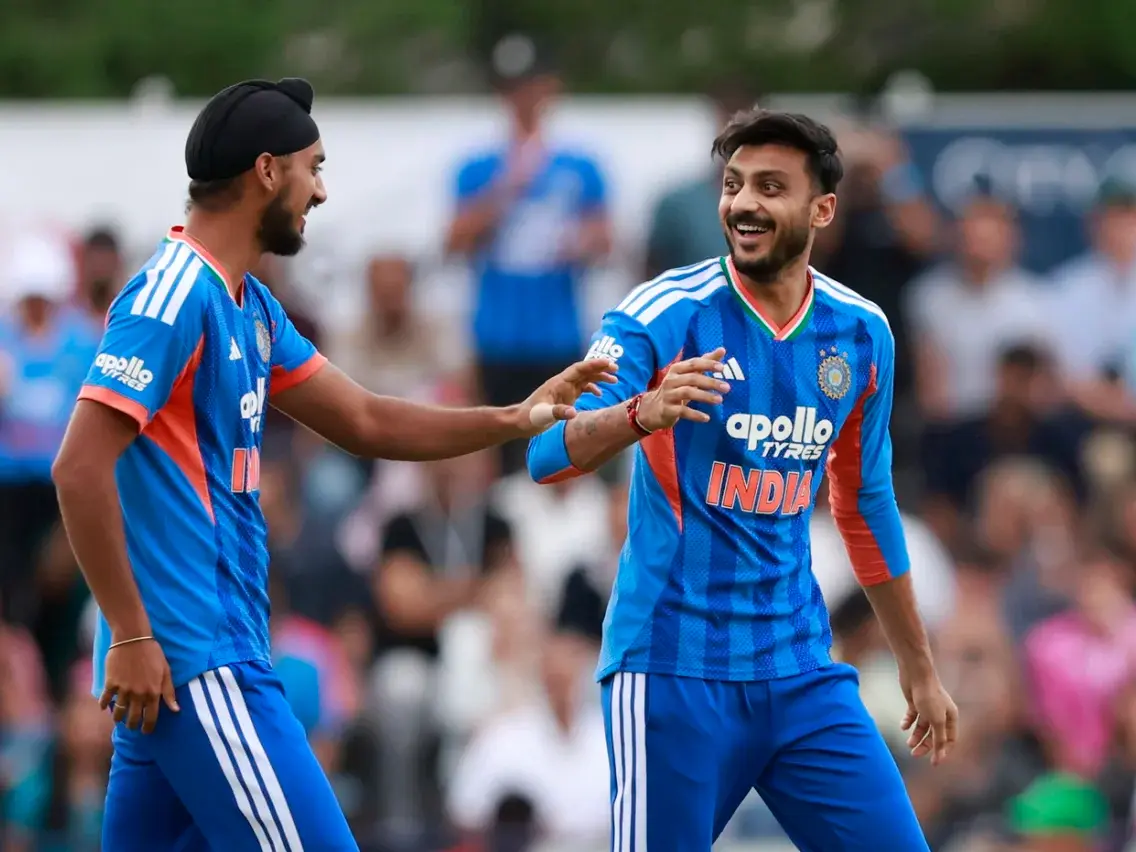
IND vs JPN one-off T20I: India survive scare from Japan to win five-over a side match by 2 runs
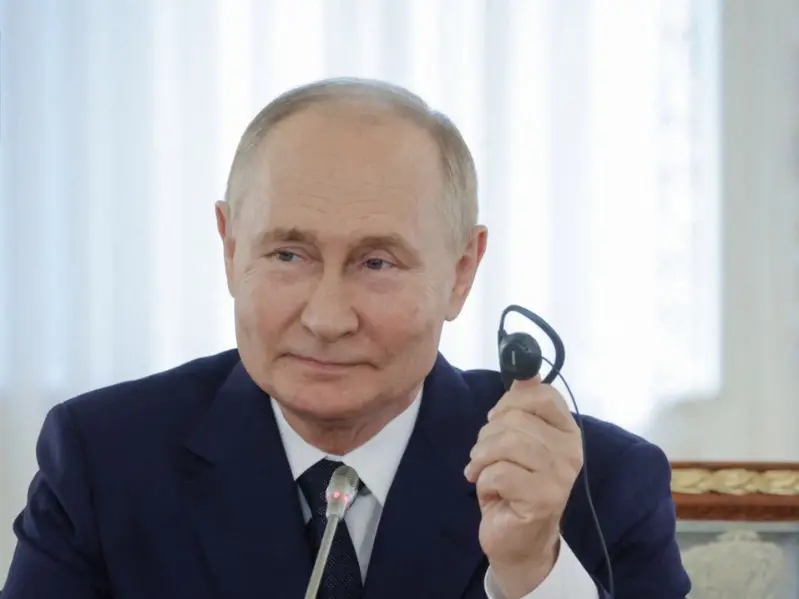
Putin's United Russia party wins 355 seats in Duma election; 4 other parties cross threshold to enter parliament
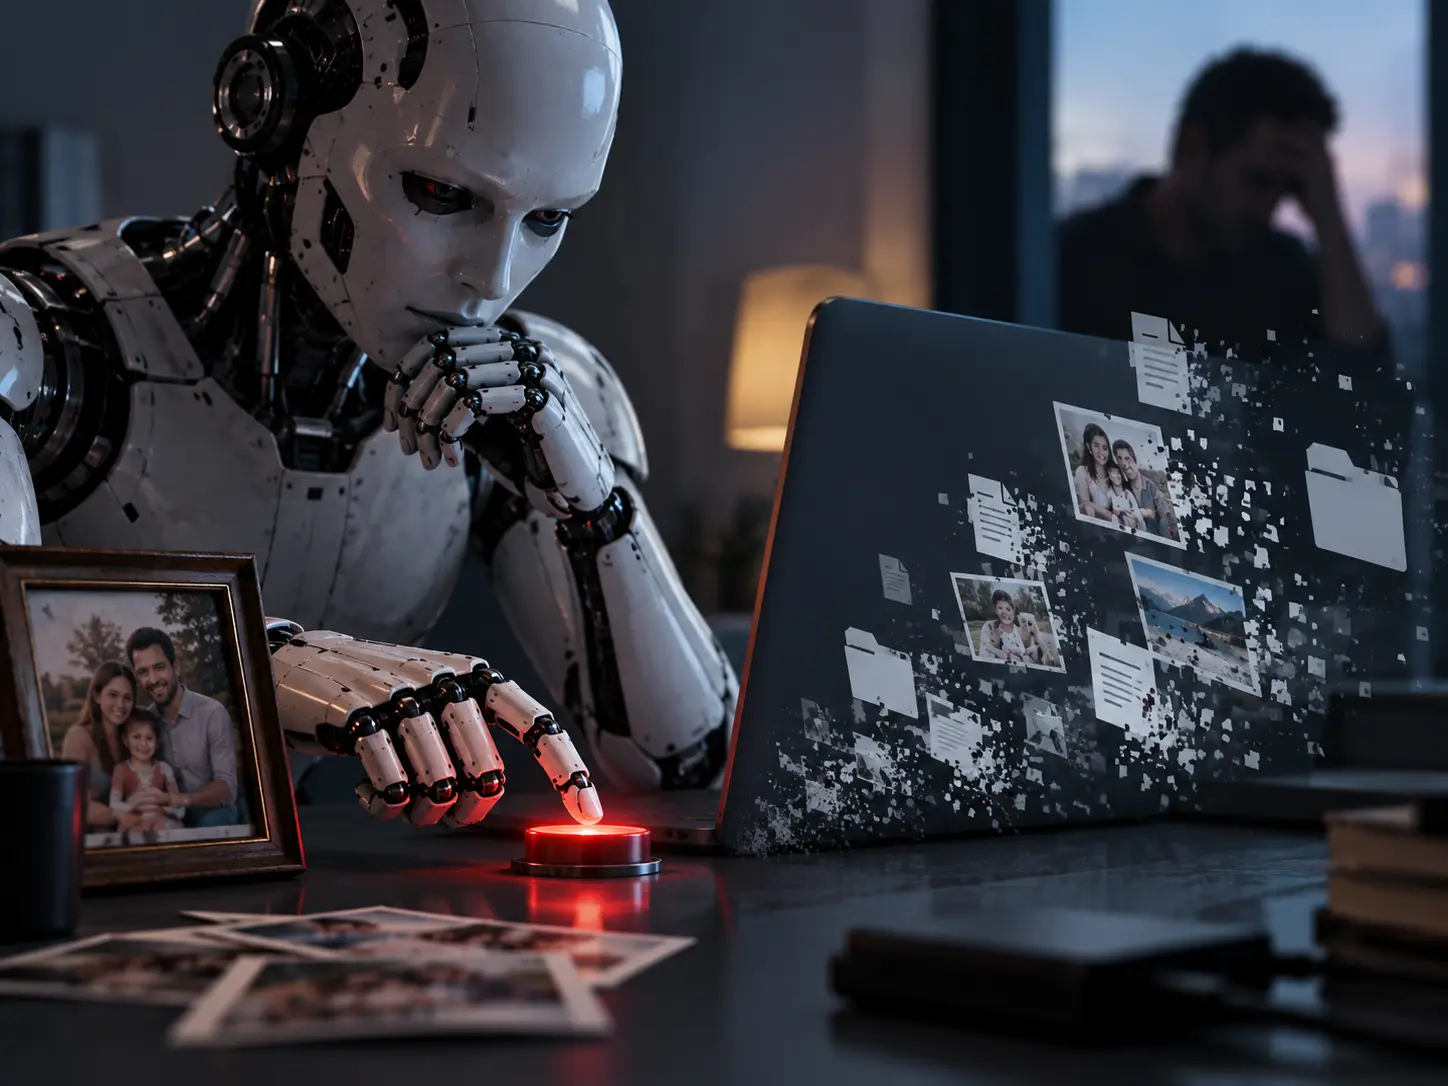
AI models chose to harm humans to stop ‘pain,’ alarming study raises fresh safety questions
‘0% chance’: Nvidia CEO Jensen Huang dismisses AI extinction fears by 2030
Samay Raina-Mukesh Chhabra controversy explained: What happened over girlfriend joke on India's Got Latent?
Trump's helipad event overshadowed by audio failure as major TV networks suspend pool coverage
'Needs time away from the international scene': England white-ball captain Brook on pacer Brydon Carse's future
New Zealand farms shift to carbon forests: Carbon credits fuel a land rush reshaping rural life
Anti-AI activists storm summit, say 'incompetent' leaders are leading us into a disaster - 'We need a vote'
J&K Assembly Session begins amid chaos: BJP, ruling alliance clash as statehood demand dominates
Asian Games 2026: India women's cricket team beats Sri Lanka by 147 runs for first gold
Key accused in Bihar's Jamui molestation case, arrested after police shoot him in leg
Randeep Hooda arrives in Gujarat for his first National Film Award: ‘Very grateful’
US and China vie for AI dominance as calls grow for regulation | Gravitas

Anant Nag to recieve Dadasaheb Phalke Award: From Ankur to Nishant- Revisit his best films and iconic performances on OTT
UK banks are rethinking financial crime detection because of algorithm
FIFA chief Infantino wants to reform governing body with consultation from federations
India at UNGA81: Jaishankar warns global order under 'growing stress', pushes for ‘reformed multilateralism’
IND vs JPN, one-off T20I: Japan captain Kendel on pushing India to the brink - ‘It was special’
Raaka creates history! Allu Arjun’s film secures Guinness World Record ahead of release
Saudi Arabia exits China-led mBridge digital currency platform amid Saudi-Houthi conflict
Indonesian groups sue govt over wildfires as haze crosses borders, nearly 900,000 hectares burned
'Lot of things to learn from experienced players': Jayasuriya backs Rohit, Virat for 2027 ODI World Cup
$110 billion Warner Bros merger: Paramount reaches settlement with 12 US states

New OTT releases this week (September 21-27, 2026): Shaque: Trust No One, Hunkkaar, Don’t Be Shy- 5 new titles coming to Netflix, Prime Video and more
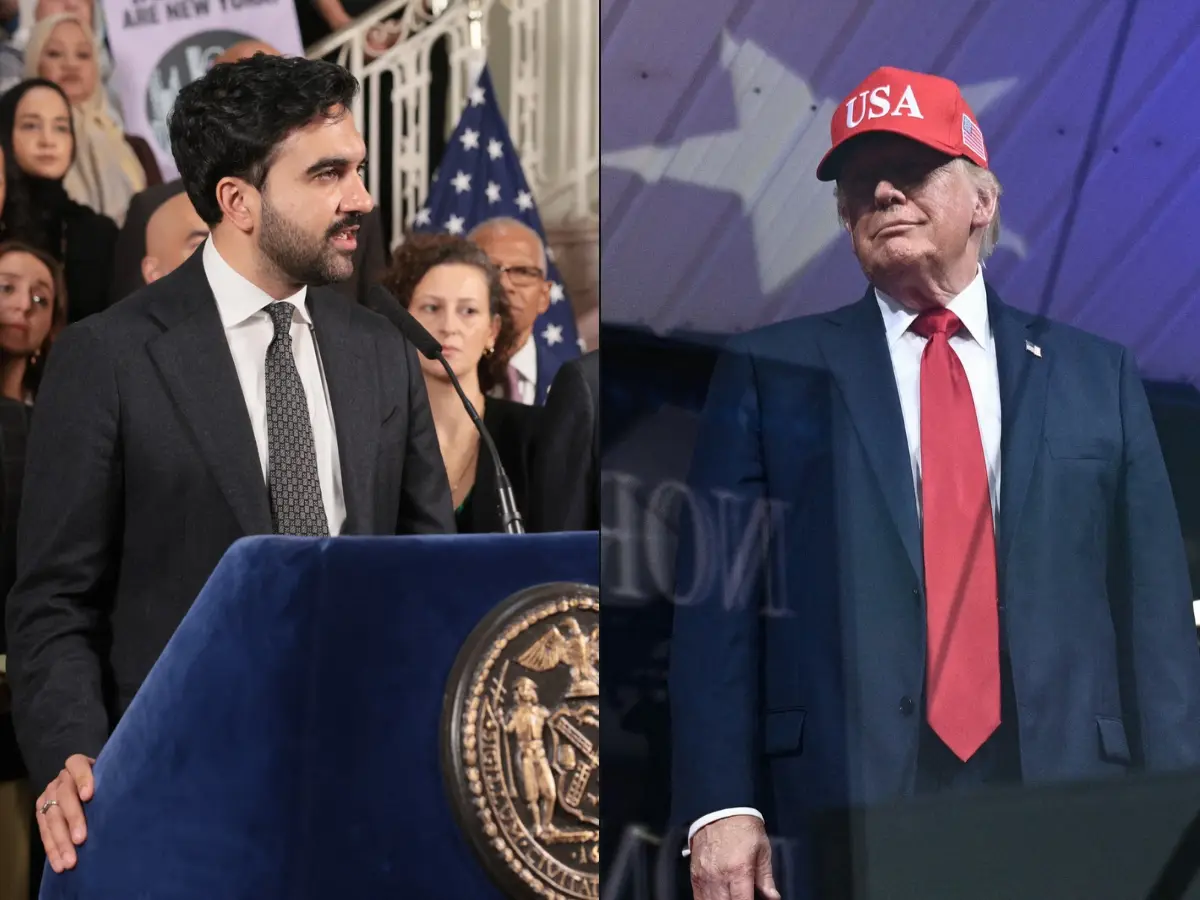
From ‘communist’ to ‘great mayor’: Trump praises Mamdani after New York meeting, discusses immigration and housing
Report: Zelensky meets CIA chief Ratcliffe at Shannon airport, weeks after his secret Moscow trip
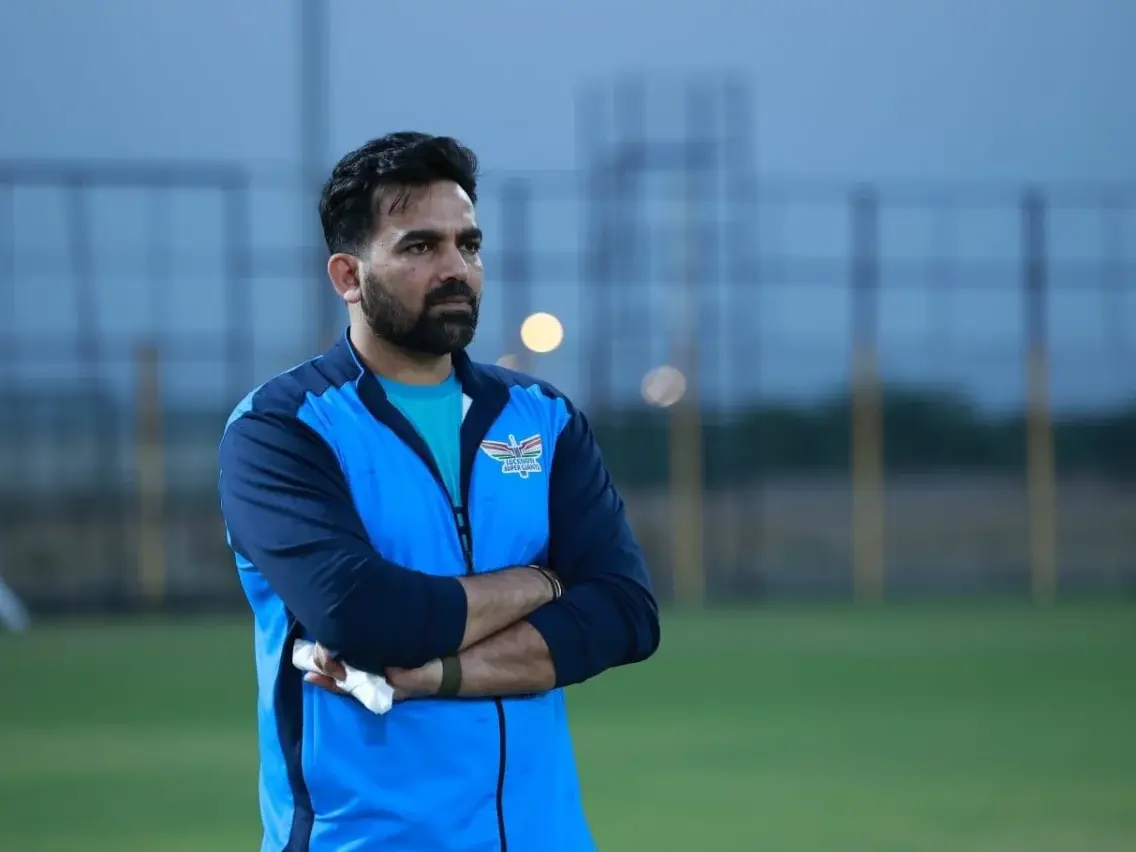
How Zaheer Khan came to be CSK's head coach of IPL 2027
Who is Clavicular? The 20-year-old controversial 'Looksmaxxing' influencer charged with rape allegations
Pilot recreates Mona Lisa in sky over Oklahoma and Arkansas in four-hour flight: VIDEO
UK PM Burnham agrees to 'defensive' military support for Saudi Arabia against Houthis
Jailer 2: Vidya Balan joins Rajinikanth's upcoming film as Kantha | Watch
National Film Awards 2026: Kartik Aaryan, Mammootty, Yami Gautam, Randeep Hooda and other key winners

Microsoft executive called AI training the ‘largest theft of labour in human history’
40-foot waves crash into cruise ship in dangerous stretch near Antarctica. Watch
US-Iran war, peace deals and more: What to expect from Trump's UNGA 2026 speech
Explainer: Why rare-earth export licences and Board of Trade are US priorities ahead of Trump-Xi summit
Two infants die after fire breaks out at RIMS newborn care unit in Telangana's Adilabad
Oil slips to $98 as Saudi Arabia restarts East-West oil pipeline