ECB initiates two-year preparation phase for digital euro: Report


Signage is seen outside the European Central Bank (ECB) building, in Frankfurt, Germany
The European Central Bank (ECB) has made a significant attempt towards introducing a digital version of the euro, a move that aims to provide secure and free electronic payment options for citizens across the Eurozone. The ECB has officially announced that a two-year "preparation phase" for the digital euro will commence on November 1.
During this period, the ECB will finalise regulations, select private-sector partners, and engage in testing and experimentation, paving the way for potential issuance and rollout of the digital currency in the future.
While this announcement marks the initial steps in a multi-year project, it sets the ECB ahead of other central banks from the Group of Seven (G7) nations and may serve as a blueprint for others to follow. Several Caribbean countries and Nigeria have already launched digital currencies, while China and Sweden have conducted pilot projects in this realm. In contrast, central banks like the Federal Reserve, the Bank of England, and the Bank of Canada have displayed more cautious approaches towards such initiatives.
The digital euro, once implemented, will function much like any online wallet or bank account, with the distinctive feature of being free to use and backed by the ECB, ensuring its safety. Nonetheless, the project faces criticism from various quarters, including bankers, regulators, some academics, the European Union’s privacy watchdog, and specific consumer groups. Their concerns revolve around the fear that digital currency might drain deposits from the commercial sector and offer limited improvements compared to existing accounts. Reuters cited Markus Ferber, a German member of the European Parliament, who remarked that the ECB has yet to effectively communicate the added value of the digital euro.
To address apprehensions regarding the impact on commercial banks, the ECB intends to place a cap on individual ownership of digital euros, likely around 3,000 euros. The ECB views the digital euro as a means to introduce competition into the payment market, which is currently dominated by U.S. credit card companies.
Similar to physical cash, digital euros will allow users to make small offline payments in close proximity to recipients, and the ECB emphasises that it will not retain transaction data. The digital euro will be distributed by the ECB, commercial banks, and digital wallet providers, but it will be accessible only to residents of the Eurozone and its overseas citizens, addressing concerns about adoption in countries with weaker local currencies.
'He will always be ahead': India coach Gambhir says Sooryavanshi won't walk into team ahead of Samson
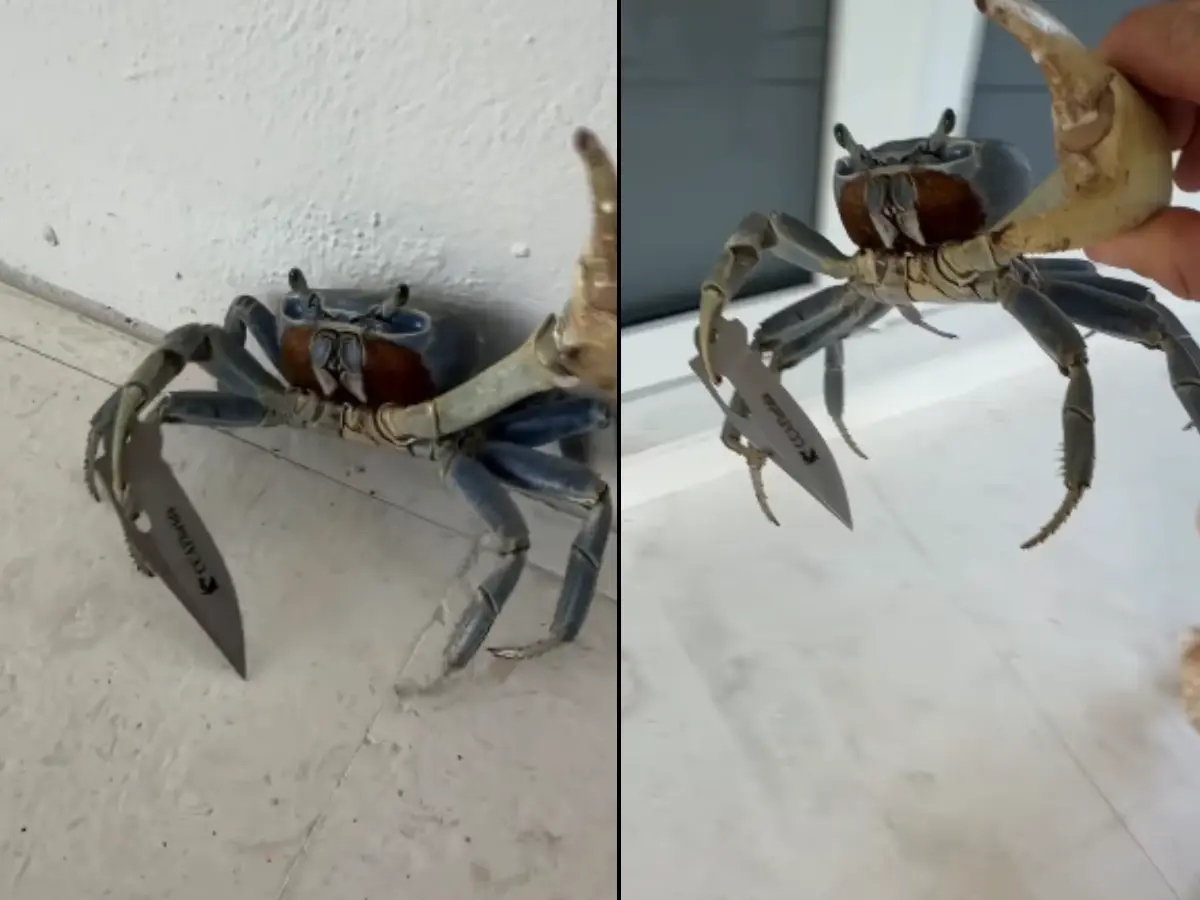
'Gangsta' crab shoves knife blade at man and his dog in Florida - Watch
Which country has the most F-35s outside America?
Andhra Pradesh police pose as FBI to get X to remove tweets
Godfather of AI Geoffrey Hinton gives US lawmakers a one-year warning on AI
UNGA 2026 theme explained: What does ‘Restoring trust, managing transformation: A United Nations that delivers for all’ mean?
US F-16 fighter jet crashes in Michigan during training mission, pilot ejects safely
Meet top 5 Indian batters with fastest T20I centuries
Laura Wolvaardt sets new world record for most WT20I runs in a year
Ganpati Visarjan: Alia Bhatt and Ranbir Kapoor bid adieu to Bappa, watch viral videos
Who is Khalilur Rahman? All you need to know about 81st UN General Assembly President
North Korea's last nuclear test in 2017 set off 1,399 earthquakes over 8 years, each stronger than previous
New Friday OTT releases (September 18, 2026): Lust Stories 3, You+Me, Best of the Best- 8 new titles coming on Netflix, Prime Video and more
Xi-Trump summit may boost military links
Pentagon revives mandatory testosterone testing for male troops aged 30 and above
Asian Games 2026: Shafali stars as India thump Japan by 8 wickets to book semis berth
Marathi film Gondhal is India's official entry for Oscars 2027
The Verdict | When precision fails: US commits war crime in Minab school strike, UN finds
Shivakumar attends 79th Kalyana Karnataka Utsav in Kalaburagi
Three labourers killed as DU student loses control of his car, rams into them on Dwarka Expressway
US-North Korea tensions explode, Kim Yo Jong warns of 'more offensive' response
From Abhishek Sharma to Sahil Chauhan, 5 batters with fastest T20I hundreds
Ukraine plans record $109 bn defence spending, nearly two thirds of budget amid Russia war
Drone strikes cooling tower at Russia's Kursk Nuclear Plant, IAEA confirms
Suriya and Jyothika say ‘I do’ again after 20 years! See their dreamy wedding pics
Cristiano Ronaldo returns to Portugal squad for Nations League under new coach
Trump bans CNN, MS NOW and Politico from White House over ‘FAKE NEWS’
Spain Floods: Deadly floods hit Spain as torrential rains trigger widespread flooding
How did an Australian river with 500 crocodiles pass the Olympic test? Here's how
Hong Kong extends newborn cash support scheme by three years
Meet top 5 bowlers in latest ICC T20I rankings
India ‘deeply concerned’ as Houthi strikes hit Saudi civilian & energy sites
A first in 100 years: New cat species discovered in Bolivia is incredibly tiny
Africa is splitting, and a lot sooner than estimated, giving way to a new ocean
Indian activist-lawyer Prashant Bhushan's post brings focus on ‘conflict of interest’ appointments of ex-govt officials at Reliance, Adani groups
Meet top 5 batters in the latest ICC T20I Rankings
‘Will go to any extent’: Pakistan vows to defend Saudi Arabia amid Houthi attacks
Former India player Diana Edulji wants Smriti Mandhana to replace Harman as skipper at the earliest
India seeks to build a full semiconductor supply chain
The push for digital currencies among central banks is gaining momentum. Central banks representing a fifth of the world's population are expected to introduce their own digital currencies within the next three years, according to a survey by the Bank for International Settlements. While such projects began to gain prominence in 2019, the rise of stablecoins, crypto tokens backed to some extent by traditional currencies, has rejuvenated the momentum of central bank digital currencies (CBDCs).
(With inputs from Reuters)
WATCH WION LIVE HERE